Workers' Compensation Insurance Calculator

Estimate Workers’ Compensation Insurance costs by multiplying payroll by the applicable job classification rate and adjusting for factors such as claims history and state requirements. A calculator or personalized quote can provide a more accurate estimate for your business.
female small business owner happy to use workers’ compensation insurance calculator

Key Takeaways

  • Workers’ Compensation Insurance costs are typically calculated by multiplying your payroll by job classification rates set by the state. 
  • Factors like industry risk, employee job duties, payroll size and your business’s claims history all influence your final Workers’ Compensation Insurance premium. 
  • Because rates and formulas vary by state, using a Workers’ Compensation Insurance cost calculator or getting a quote can help estimate your business’s actual insurance cost. 

How Are Workers' Compensation Insurance Premiums Usually Calculated?

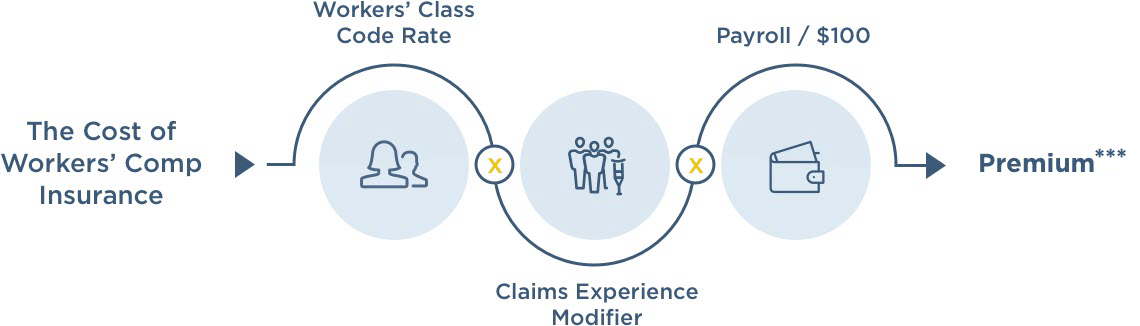
You can estimate your workers’ compensation insurance costs through this formula:
 
Workmen's Compensation Calculation
 
Each state has its own classification code depending on the type of work performed by your employees. The National Council on Compensation Insurance (NCCI) assigns these codes.
 
Your state may also determine your business’ unique experience by comparing your company to others in your industry.
 
Your business’ payroll gets multiplied by a rate that matches the class code. Each class code has a rate per $100.
 
Together, these items help determine workers’ compensation rates.

How Much Is Workers’ Comp Insurance?

Most of our customers with less than $300,000 annually in payroll pay an average of $81 a month for workers’ compensation insurance, also known as workers’ comp insurance.** Workers’ compensation insurance costs vary by state due to local requirements, payroll and industry risk. Use the tool to see the average cost for small businesses in your state.
$00/mo1
on average
How Is Workers' Comp Calculated video

How Is Workers' Comp Calculated?

How much workers' comp pays for an injured employee is based on a simple formula or workers' comp calculator, using their average weekly wage on the date of the injury. Watch the video to learn about how workers’ comp is calculated.

How Much Does Workers’ Comp Pay?

No matter what type of business you run, on-the-job injuries or illnesses can happen. This is where workers’ compensation insurance can step in and give your employees important benefits. An injured or ill employee can file a workers’ compensation claim and receive weekly payments to cover medical bills or lost wages. This coverage is also known as workers’ comp insurance and workman’s compensation. Remember, this coverage won’t help if your employee gets a personal injury that’s not related to their work. But it can help protect your business from liability if you’re sued by an employee for a work injury.
 

Average Weekly Wage

Small business workers’ compensation benefits give your employees a percentage of their average weekly wage. However, the weekly payment amounts they receive will depend on regulations from your state workers’ compensation insurance.
 
This example can help you learn how to calculate your employees’ average weekly wage:
 
Your full-time employee made $50,000 last year after working for 242 days. If you divide $50,000 by 242, their average daily wage is $206.61.
 
Next, multiply $206.61 by 260 (the number of days a full-time employee would work in a year). That should equal $53,718.60.
 
Finally, divide $53,718.60 by 52 (the number of weeks in a year), to get your employee’s average weekly wage of $1,033.05.
 

Partial vs Total Disability

The weekly amount your employees receive is also based on the type of injury or illness they have. If they’re partially or totally disabled, they’ll get different benefits than someone with a temporary injury. In fact, a totally disabled employee will typically get 60% or 2/3 of their average weekly wage. Each state also has a maximum weekly rate, so you’ll want to make sure you understand the rules and benefit amount for your state.
 
If you’re wondering how long workers’ comp lasts, that also varies. Generally, the more severe a work-related injury or illness is, the longer payments last. If you expect your employee to need future medical treatment beyond regular workers’ comp payments, you may want to advise them to talk to a lawyer for legal advice.
 

What Are The Premium Rate Factors?

So, how is workers’ comp calculated? To figure out workers’ comp premiums, you’ll first need to understand the factors that influence them, such as:
 
Each state has its own classification code depending on the type of work performed by your employees. The National Council on Compensation Insurance (NCCI) assigns these codes.
 
Your state may also determine your business’ unique experience mod by comparing your company to others in your industry.
 
Your business’ payroll gets multiplied by a rate that matches the class code. Each class code has a rate per $100.
 
Together, these items help determine workers’ comp insurance cost.
Average Monthly Workers' Compensation Cost for The Hartford's Customers:**
For payroll amount:
Approximate Monthly Cost
~ ?
State Average Issued Premium**
AL $1,448
AR $998
AZ $1,116
CA $1,600
CO $759
CT $1,555
DC $1,081
DE $976
FL $1,149
GA $1,041
IA $505
ID $1,211
IL $1,062
IN $862
KS $946
KY $837
LA $1,069
MA $990
MD $839
ME $1,220
MI $740
MN $1,181
MO $1,428
MS $1,435
MT $1,033
NC $1,009
NE $809
NH $1,149
NJ $1,079
NM $1,423
NV $906
NY $998
OK $1,150
OR $1,166
PA $935
RI $1,721
SC $1,234
SD $703
TN $1,109
TX $576
UT $666
VA $840
VT $1,300
WI $1,173
WV $557
female small business owner happily using workers comp cost calculator

Learn More About Workers’ Compensation From The Hartford

Contacting insurance companies to learn how to get workers’ comp insurance or filing a claim can be a hassle. We can help make workers’ compensation cases simple.
 
In fact, small businesses have relied on us for over 200 years. Our team can help you get the workers’ compensation coverage you need to protect your business and employees. You can also learn more by looking through our workers’ compensation definition and FAQs page.
 
Get a workers’ comp quote today and learn how we can help protect your business.
*** This is a simplified calculation for educational purposes only. Actual premium calculations can be more complex. Experience mods are subject to state requirements and do not apply to every policy.
 
Additional disclosures below.
The Hartford shall not be liable for any damages in connection with the use of any information provided on this page. Please consult with your insurance agent/broker or insurance company to determine specific coverage needs as this information is intended to be educational in nature.
 
The information contained on this page should not be construed as specific legal, HR, financial, or insurance advice and is not a guarantee of coverage. In the event of a loss or claim, coverage determinations will be subject to the policy language, and any potential claim payment will be determined following a claim investigation.
 
Certain coverages vary by state and may not be available to all businesses. All Hartford coverages and services described on this page may be offered by one or more of the property and casualty insurance company subsidiaries of The Hartford Insurance Group, Inc. listed in the Legal Notice.
 
The Hartford Insurance Group, Inc., (NYSE: HIG) operates through its subsidiaries under the brand name, The Hartford, and is headquartered in Hartford, CT. For additional details, please read The Hartford’s Legal Notice.
 
* Customer reviews are collected and tabulated by The Hartford and not representative of all customers.